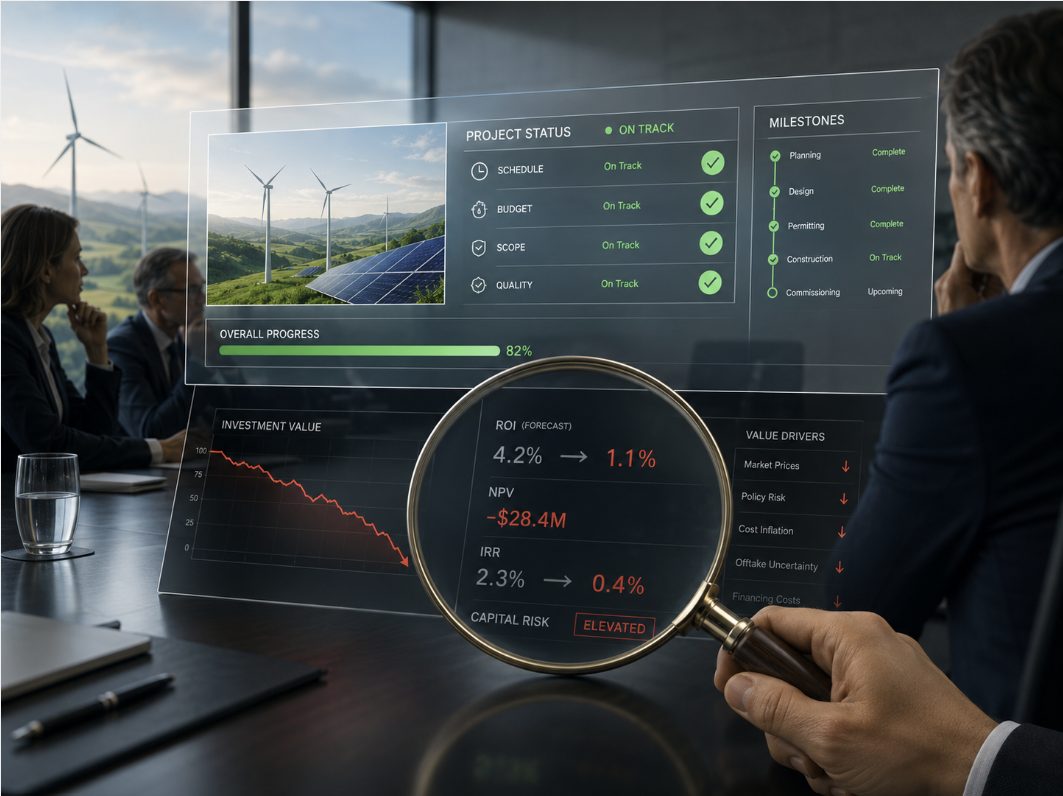
For years, PMO leaders have argued that they need more authority, stronger executive sponsorship, better tools, and a more influential seat at the table. The profession has treated these things as the path to greater relevance. The assumption is that if the PMO can obtain better data, improve reporting, standardize delivery, and gain more executive attention, it will finally be able to prevent the failures that repeatedly damage enterprise transformation.
That assumption is incomplete.
A PMO can receive more authority and still administer the wrong investment more efficiently. It can produce faster reports while the underlying economics deteriorate. It can enforce stronger delivery discipline while leadership continues funding an initiative whose original business case no longer holds. It can create a sophisticated dashboard that accurately describes execution activity without ever forcing the organization to confront whether the investment itself remains defensible.
The central problem is not simply that the PMO lacks influence. The deeper problem is that most organizations continue to view projects through a delivery lens when they should also be examining them through a fiduciary lens.
The delivery lens asks whether the work is progressing. The fiduciary lens asks whether the capital should remain committed.
Those are not the same question.
Delivery Progress Is Not Investment Validity
Traditional project governance is built around execution. It asks whether milestones are being achieved, whether risks are being managed, whether the schedule is holding, whether the budget remains within tolerance, and whether the team expects to complete the agreed scope. These are necessary questions, but they are not sufficient for protecting enterprise capital.
A project may continue to deliver outputs even after its investment thesis has begun to collapse.
The team may complete design, configure technology, migrate data, close defects, and report measurable progress. At the same time, adoption assumptions may be weakening, operating costs may be increasing, business readiness may be slipping, market conditions may be changing, and the expected benefit window may be narrowing. The project can remain active and productive while becoming progressively less valuable to the enterprise.
This creates one of the most dangerous conditions in modern governance: a project that appears healthy when measured as a delivery system but has become questionable when measured as an investment.
The distinction matters because leadership rarely funds activity for its own sake. It funds expected outcomes. Capital is committed because the organization believes an initiative will create value, reduce exposure, satisfy an obligation, strengthen capability, improve resilience, or produce some other strategically important result.
The original funding decision is therefore based on a set of assumptions. Those assumptions may concern cost, timing, adoption, demand, regulatory pressure, operating savings, technical feasibility, business capacity, or expected benefits. Once execution begins, however, governance often shifts away from those assumptions and focuses almost entirely on the mechanics of delivery.
The business case becomes a historical approval document rather than a living investment hypothesis.
As long as the project continues moving, leadership may assume the original decision remains valid. Yet motion does not prove validity. Delivery progress does not confirm that the benefits remain achievable, that the timing still makes economic sense, or that the next dollar of funding will produce an acceptable return.
A green project can still be a bad investment.
The Status Report Cannot Answer the Most Important Question
Most project status reports were never designed to determine whether continued investment remains justified. They are designed to summarize execution conditions.
A conventional status report can tell leadership that a project is on schedule, within budget, carrying several manageable risks, and approaching its next milestone. It may describe completed tasks, open issues, resource concerns, and planned activities. It may provide a red, amber, or green rating intended to compress a complicated delivery environment into a manageable executive view.
What it usually does not reveal is whether the original investment thesis is still intact.
It does not necessarily show that the expected financial benefit has declined by thirty percent since approval. It may not reveal that six months of delay have materially reduced the remaining value window. It may not make visible that the organization has funded recovery work several times without changing the underlying conditions that caused the failure. It may not distinguish between money that is advancing the intended outcome and money that is merely preserving organizational momentum.
The status report describes the project as a managed body of work. Leadership, however, has a more consequential obligation. It must decide whether to continue exposing capital to that body of work.
That decision cannot be made responsibly through schedule variance, budget variance, milestone progress, and management confidence alone.
It requires a fiduciary lens.
What the Fiduciary Lens Changes
A fiduciary lens changes the governing question from “Can the project continue?” to “Should the enterprise continue funding it under the current conditions?”
That change may appear subtle, but it transforms the purpose of governance.
A project team is usually organized to achieve delivery. Its incentives, commitments, professional identities, vendor relationships, and operating rhythms are aligned around continuation. Even when serious concerns emerge, the natural response is to recover the plan, revise the forecast, resolve the issue, secure more resources, or move the milestone. These responses may be entirely reasonable from a delivery perspective.
They may not be reasonable from a capital perspective.
The fiduciary lens does not assume that continuation is the default. It examines whether the evidence still supports continuation. It asks whether the expected value remains credible, whether the remaining cost is proportionate to that value, whether the organization can still absorb the change, whether major assumptions have expired, and whether a different use of capital would now be more defensible.
It also recognizes that the relevant decision is not whether the enterprise should regret what it has already spent. Sunk cost is not a governance strategy. The important decision concerns the next commitment of money, time, executive attention, organizational capacity, and operational risk.
The fiduciary lens therefore asks questions that traditional delivery governance often avoids.
Does the original investment thesis still hold?
What evidence supports the current benefit forecast?
How has delay changed the economics of the initiative?
What additional capital is required before value can be realized?
Are the expected benefits deteriorating faster than delivery is progressing?
Have the project’s most important assumptions been retested, or are they merely being carried forward?
Is the organization funding outcome creation, or is it funding the preservation of the project?
Would continuation remain defensible if the initiative were presented for approval today?
These questions do not undermine delivery. They place delivery inside the larger responsibility to protect enterprise capital.
Procedural Compliance Is Not Fiduciary Protection
One reason weak investments survive is that organizations confuse procedural compliance with responsible governance.
A project may have an approved charter, a current schedule, a functioning steering committee, a RAID log, a benefits statement, a change-control process, and a formally documented budget. It may satisfy every required governance ceremony. None of that proves the investment remains sound.
Procedure can confirm that the organization followed its process. It cannot, by itself, confirm that leadership is still making the right capital decision.
This distinction becomes especially important in large transformations, where the presence of governance activity can create a false sense of protection. Executives see status reports, committee meetings, risk registers, financial forecasts, and program reviews, and they reasonably conclude that the investment is being governed.
In many cases, however, the system is primarily governing delivery behavior. It is monitoring whether the project team is performing the work according to the organization’s expectations. It is not continuously testing whether the organization’s continued exposure remains justified.
This is how an initiative can become operationally active, procedurally compliant, and financially indefensible at the same time.
Nothing necessarily appears broken inside the governance machinery. Reports are produced. Meetings are held. Decisions are recorded. Risks are discussed. Forecasts are updated. Yet the central capital question remains unasked because the governance system was not designed to ask it.
The enterprise knows what the project is doing. It does not necessarily know whether the project still deserves the capital assigned to it.
The Problem Is Not Always Failure
The fiduciary lens is not merely a mechanism for identifying failing projects. That interpretation would be too narrow and would recreate the same reactive governance model under a different name.
A project does not need to be failing before its investment thesis requires reconsideration.
The environment may have changed. A competitor may have altered the market. A regulatory requirement may have shifted. A planned acquisition may no longer be occurring. A technical dependency may have become more expensive. A business unit may no longer possess the capacity required for adoption. A platform decision may have changed the architecture. An expected operating benefit may have been reduced by organizational constraints that were not visible during approval.
In these situations, the project team may not have done anything wrong. The initiative may have been competently managed. The original decision may have been reasonable based on the information available at the time.
The governance responsibility is not to assign blame. It is to determine whether the current decision remains defensible under current evidence.
That is why the fiduciary lens must be separated from punitive project review. Its purpose is not to catch teams making mistakes or to provide executives with a new mechanism for cancellation. Its purpose is to protect the integrity of the next capital decision.
Sometimes the evidence will support continuation. Sometimes it will justify additional investment. Sometimes it will reveal that a bounded recovery effort is appropriate. In other cases, it may support a pause, a scope reduction, a renegotiation, a strategic pivot, or an orderly termination.
The outcome should not be predetermined. The discipline lies in making the decision visible, evidence-based, and defensible.
Why Executive Confidence Is Not Evidence
Traditional governance often relies heavily on management confidence. Leaders ask program executives whether they believe the project can recover, whether the new date is credible, whether the team has addressed the root cause, or whether the revised plan can succeed.
These judgments matter. Experienced leaders understand context that cannot be reduced to a metric. The problem arises when confidence becomes a substitute for evidence.
Confidence is particularly unreliable inside a system that rewards continuation. Sponsors have reputational exposure. Delivery leaders have made commitments. Vendors have commercial interests. Teams have invested years of work. Executives may have publicly associated themselves with the initiative. Each participant may sincerely believe that one more recovery plan, one more funding increment, or one more schedule revision will finally restore the expected outcome.
This does not require dishonesty. It requires only human attachment to prior decisions.
The fiduciary lens introduces disciplined distance. It does not reject management judgment, but it requires that judgment to be tested against observable conditions. It examines whether delivery evidence, financial evidence, behavioral evidence, and narrative evidence support the same conclusion.
When those forms of evidence begin to diverge, the organization may be experiencing a Truth Gap.
The financial forecast may show growing exposure while the executive narrative remains optimistic. The schedule may report progress while business readiness continues to decline. The risk register may show controlled conditions while decisions are repeatedly deferred. The program may describe temporary disruption while recovery funding becomes a recurring operating pattern.
These divergences are not merely reporting imperfections. They are forensic signals that the capital decision requires closer examination.
Delay Is Not Just a Schedule Problem
One of the most significant weaknesses in traditional project governance is the treatment of delay as an execution problem rather than a capital event.
When a milestone slips, the organization typically focuses on the mechanics of recovery. The team recalculates dates, examines dependencies, adds resources, revises sequencing, and presents a new forecast. The primary concern is how to restore the schedule.
The fiduciary lens asks a different question: what did the delay do to the investment?
A six-month delay may increase implementation cost, extend duplicate operating environments, defer revenue, prolong exposure to a known risk, consume scarce business capacity, trigger contractual consequences, or reduce the remaining period in which benefits can be realized. The delayed project may eventually deliver the same technical scope while producing materially less enterprise value.
From a delivery perspective, the project may have recovered once a new achievable date is established. From a capital perspective, the project may never recover because the economic damage caused by the delay cannot be reversed.
This is the point at which schedule management becomes capital governance.
The question is no longer whether the project can finish. The question is whether finishing under the new conditions still justifies the remaining investment.
Without a fiduciary lens, organizations repeatedly approve schedule recovery while failing to reevaluate economic validity. Delay is documented, explained, and absorbed, but its effect on capital is never fully adjudicated.
The project survives. The original value proposition quietly does not.
The PMO’s Future Is Not Administrative Authority
This is where the future role of the PMO becomes more consequential.
The PMO will not earn durable executive relevance by becoming the most efficient producer of status information. Artificial intelligence, integrated platforms, workflow automation, and increasingly capable enterprise tools will continue to compress the administrative work associated with project reporting. Organizations will be able to produce summaries, detect variances, consolidate updates, and generate executive views with less manual effort.
The administrative function will not disappear, but it will become increasingly difficult to defend as the highest-value contribution of the PMO.
The opportunity is not to preserve the reporting layer. It is to elevate the governance layer.
A strategically relevant PMO can provide leadership with an independent, evidence-based view of whether committed capital remains governable. It can identify where delivery progress and investment validity have begun to diverge. It can surface the assumptions that must be retested before additional funding is approved. It can distinguish temporary execution noise from evidence that the investment thesis has materially changed.
This does not mean the PMO should seize the authority of the CFO, the sponsor, the board, or the investment committee. The PMO does not own the capital decision.
It should help make that decision defensible.
That is a more valuable role than advocating for a seat at the table. It gives the organization a reason to bring the PMO into the decision because the PMO contributes a form of governance that is otherwise missing.
Authority should follow the value of the function. It cannot substitute for it.
From Project Assurance to Capital Assurance
Many organizations already conduct project assurance reviews, health checks, stage gates, and independent assessments. These mechanisms can be useful, but they often remain anchored in delivery viability.
They ask whether governance is functioning, whether plans are credible, whether controls exist, whether risks are understood, and whether the project appears capable of achieving its objectives. Once again, these are important questions.
Capital assurance goes further.
It examines whether the initiative’s continued funding remains justified relative to the current evidence. It does not merely test whether the team can execute the plan. It tests whether the plan is still worth executing.
This requires governance to reconnect the project with the decision that created it. The business case cannot remain frozen at approval. Benefits cannot be treated as distant promises that will be examined only after implementation. Assumptions cannot remain implicit while conditions change around them.
The investment thesis must remain open to challenge throughout the life of the initiative.
That does not mean recreating the entire approval process every month. It means identifying the conditions that would materially alter the funding decision and continuously observing whether those conditions have emerged.
The enterprise should know what evidence would justify continued funding, what evidence would trigger deeper review, and what evidence would require a formal capital decision. Without those thresholds, governance becomes dependent on individual courage. Someone must decide that the situation feels serious enough to raise, often against the momentum of the program and the expectations of leadership.
A mature capital-governance system does not depend entirely on courage. It establishes the conditions under which reconsideration becomes an obligation.
The Next Dollar Is the Governance Decision
Organizations often become trapped by the amount already invested. The greater the expenditure, the more difficult it becomes to reconsider the initiative. Prior funding creates psychological and political momentum. Leaders fear that changing direction will make the original decision appear wrong.
A fiduciary lens reframes the issue.
The governing question is not whether the organization can recover what has already been spent. In most cases, it cannot. The governing question is whether the next dollar, the next quarter, the next contract extension, and the next allocation of executive attention are justified by the evidence available now.
This is why a project should not continue merely because stopping would be uncomfortable. Nor should it stop merely because it has encountered difficulty. Both reactions avoid the actual governance work.
The decision must be based on the relationship among remaining cost, achievable value, current risk, organizational capacity, and credible alternatives.
The fiduciary lens turns continuation into an affirmative decision rather than an assumed state. It requires leadership to recognize that doing nothing is still a capital allocation choice. Allowing the project to proceed without reconsideration does not preserve neutrality. It commits additional enterprise resources under the existing assumptions.
Once those assumptions become questionable, passive continuation becomes an unexamined investment decision.
Governance Must Protect the Decision, Not the Narrative
Projects create narratives. They need them to organize action, sustain commitment, and maintain executive support. A coherent narrative explains why the work matters, how the team will succeed, and why current difficulties can be overcome.
The narrative becomes dangerous when governance begins protecting it instead of testing it.
Leaders may receive carefully constructed explanations for missed milestones, changing costs, reduced scope, delayed benefits, and recurring recovery actions. Each explanation may be reasonable in isolation. Over time, however, the accumulation of explanations can conceal a more important pattern: the initiative being funded today is no longer the initiative that was originally approved.
Its cost is different. Its timing is different. Its scope is different. Its operating model is different. Its benefits are different. Its risk profile is different.
Yet the organization continues referring to the original business case as if the investment has remained substantially unchanged.
The fiduciary lens interrupts this narrative continuity. It asks whether the current initiative would still receive approval if leadership were evaluating it for the first time under present conditions.
That question is uncomfortable because it removes sunk cost, institutional loyalty, and prior commitment from the center of the decision. It forces the enterprise to compare the project that actually exists with the value it can still realistically produce.
Governance should not be designed to preserve the appearance of consistency. It should protect the quality of the decision.
This Is the Work of Forensic Capital Governance
Forensic Capital Governance begins with a simple premise: enterprise investments should not be allowed to drift indefinitely between formal approval and visible failure.
There is usually a long period between those two points. During that period, the initiative generates signals. Financial reality begins to diverge from the approved narrative. Decisions slow. Recovery actions repeat. Benefits become less specific. Forecasts move. Dependencies expand. Evidence becomes fragmented across meetings, financial systems, delivery tools, contracts, and executive communications.
The project may not yet have failed, but the conditions supporting the original investment decision may already be deteriorating.
Forensic governance examines those conditions before the loss becomes undeniable. It does not wait for the postmortem. It uses available evidence to determine whether the enterprise is still funding a credible outcome or merely sustaining an established structure.
The purpose is not automatic cancellation. It is not executive surveillance, project policing, or retrospective blame.
The purpose is governance protection.
Leadership must be able to explain why capital was continued, constrained, redirected, recovered, or stopped. That explanation should rest on more than confidence, precedent, or the most persuasive narrative in the room. It should be grounded in evidence that can survive scrutiny after the decision is made.
This is what makes the fiduciary lens different from another project-management method. It does not tell the team how to build the schedule, run the meeting, manage the backlog, or update the plan.
It tells the enterprise when the condition of the investment requires a capital decision.
The Question Every Executive Should Ask
At the next steering committee, portfolio review, transformation council, or investment meeting, leadership should ask a question that rarely appears on the standard agenda:
What evidence demonstrates that continued funding remains defensible?
Not whether the team is busy. Not whether the plan has been updated. Not whether the sponsor remains confident. Not whether the project can technically reach completion.
What evidence shows that the remaining investment is still justified under the conditions that exist now?
A mature organization should be able to answer that question without reconstructing the business case from scratch, relying on a heroic analyst, or waiting for a crisis to make the truth visible.
It should know what changed, which assumptions still hold, what value remains achievable, what capital remains exposed, and which decision the evidence supports.
That is the standard enterprise governance must reach.
The future PMO will not become strategically relevant because it produces faster reports, more attractive dashboards, or more disciplined administrative controls. It will become relevant when it helps leadership see the difference between delivery motion and investment validity.
A green project may still be producing work. It may still be meeting its revised milestones. It may still have an experienced team, an engaged sponsor, and a credible path to technical completion.
It can still be a bad investment.
The fiduciary responsibility of leadership is not to keep projects alive. It is to ensure that the next commitment of enterprise capital remains defensible.
That is not project administration.
That is capital governance.