In Capital Crime, Jed Simms and Alexandra Chapman pose a deceptively simple question.
Organizations generate business cases. Executives approve programs and projects. Sponsors and governance leaders sit on steering committees, examine status reports, authorize changes, and release additional funding.
Yet after all that activity, what returns do they actually know they have realized from those investments?
It is an uncomfortable question because many organizations cannot answer it with confidence.
They can usually report what was spent. They can describe what was delivered. They may know whether the system went live, whether the program completed its milestones, whether the vendor fulfilled its contractual obligations, and whether the project closed within approved tolerances.
What they often cannot demonstrate is whether the investment produced the measurable improvement that originally justified the expenditure.
This is hardly a new problem. Benefits realization has been part of portfolio and programme management doctrine for decades. Business cases are supposed to define expected outcomes. Benefits should have owners. Measures should have baselines and targets. Sponsors should remain accountable after implementation. Governance bodies should compare actual outcomes with the investment case.
The theory is familiar.
The operating reality is very different.
In many organizations, the business case remains primarily an approval artifact. It helps secure funding, establish priority, and move an initiative into delivery. Once the project begins, attention shifts toward scope, schedule, cost, risk, dependencies, technical readiness, and implementation.
When the solution goes live, responsibility becomes even less clear. The project team moves on. The program closes. The vendor completes its engagement. The operational team inherits the system. The benefit owner may still appear in a document, but the evidence required to determine whether the promised improvement occurred is scattered across functions, systems, and reporting cycles.
The organization has delivered something.
Whether it has realized value is another question.
There is also a second question that benefits-realization advocates do not always confront:
Would proving the benefit be worth what it costs to prove it?
That question changes the discussion.
Benefits measurement is not free. It consumes time, money, analytical capacity, data-engineering effort, executive attention, and organizational patience. In some circumstances, the effort required to reconnect the original business case with operational outcomes may produce less value than the measurement exercise consumes.
Therefore, benefits realization cannot simply become another unquestioned management obligation.
The measurement must earn its keep.
The “Benefits Inside” Fallacy
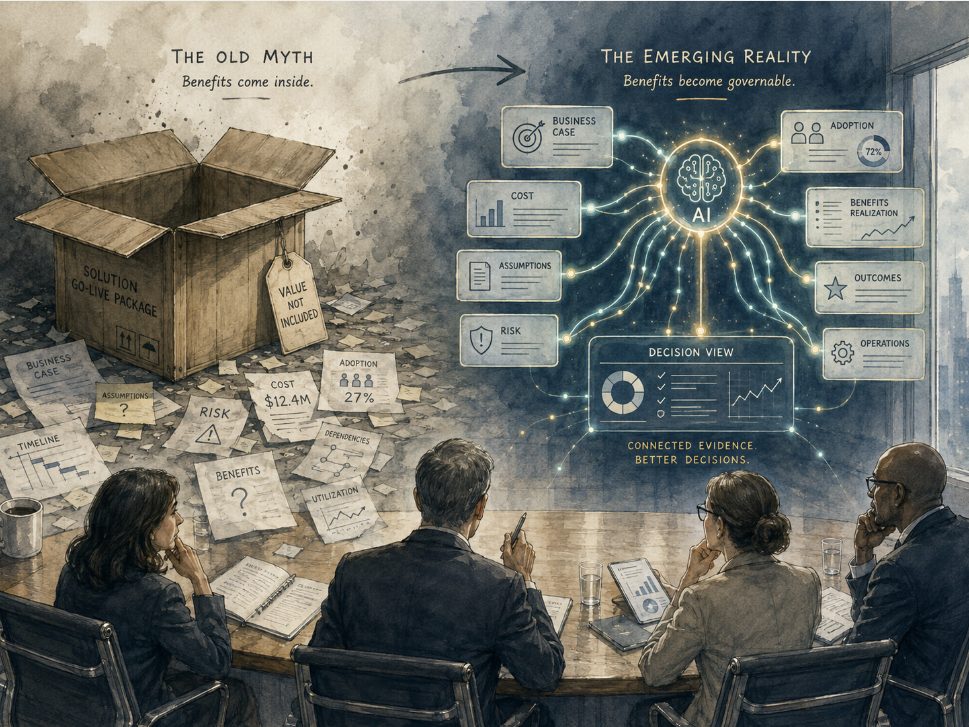
Simms and Chapman describe a persistent organizational belief that technology solutions arrive neatly packaged with “benefits inside.” The assumption is that once the program or project delivers the solution, the expected benefits will somehow emerge automatically.
This belief remains remarkably resilient.
A new platform is implemented, and productivity is expected to improve. A workflow is automated, and operating costs are expected to fall. A new data environment is launched, and decision quality is expected to increase. An artificial-intelligence capability is deployed, and efficiency, innovation, or competitive advantage is expected to follow.
The implementation may be necessary, but it is not the benefit.
A system going live does not prove that people adopted it effectively. Adoption does not prove that behavior changed. Behavioral change does not necessarily prove that operating performance improved. Even measurable improvement does not automatically establish that the investment caused it.
Furthermore, the organization may receive a useful capability without receiving the specific economic or operational return described in the original business case.
Delivery and value are related, but they are not interchangeable.
Nevertheless, many governance systems treat implementation as the point at which the difficult part is complete. The project is classified as successful, closed, and transferred into operations. Benefits realization becomes a future management responsibility, often without the evidence architecture, analytical capacity, or sustained executive attention required to perform it.
Consequently, the organization ends up governing delivery more rigorously than it governs the reason for delivery.
Why Assigning a Benefit Owner Was Never Enough
The traditional response is to assign a benefit owner.
That is directionally correct. Someone should be accountable for determining whether the expected improvement is occurring, explaining material variance, and initiating action when the benefit case weakens.
However, assigning accountability does not automatically create the capability needed to exercise it.
The evidence may be distributed across financial systems, operational platforms, project records, customer data, service-management tools, workforce metrics, vendor reports, meeting transcripts, technical logs, risk records, and informal decisions.
Measures may have been defined differently across functions. The original baseline may no longer be reliable. The operating environment may have changed since the business case was approved. Some benefits may be visible quickly, while others require sustained adoption, organizational change, process stabilization, or market response.
By the time the expected benefit should be visible, the people who constructed the original assumptions may no longer be involved.
The benefit owner is therefore expected to reconstruct a relationship among the original business case, subsequent decisions, implementation evidence, operating outcomes, changing assumptions, and current financial performance.
In principle, that is possible.
In practice, it is labor-intensive, politically difficult, and rarely supported by a coherent information architecture.
The problem is not simply that nobody owns the benefit.
The deeper problem is that the enterprise has not made the benefit governable.
Ownership without evidence becomes ceremonial accountability. Yet evidence gathered without regard for cost can become ceremonial measurement.
Both failures matter.
The Business Case Is a Funded Belief
A business case is often treated as though approval transforms it into a durable fact.
It does not.
A business case is a structured belief about the future. It contains propositions about cost, timing, adoption, capability, dependencies, risk, operating change, and expected return. Leadership authorizes capital because those propositions appear sufficiently supportable at a particular decision point.
In Forensic Capital Governance, I refer to this as a Funded Belief.
The term is not intended to diminish the quality of the original analysis. Every investment decision must operate under uncertainty. Forecasts are estimates. Benefits depend on assumptions. Plans are representations of a future that has not yet occurred.
The governance problem begins when the enterprise forgets that the belief remains conditional.
Approval establishes support at one point in time. It does not establish permanent validity.
After authorization, the operating environment continues to change. A dependency becomes more difficult than expected. Adoption is slower. A vendor constraint emerges. A technical assumption weakens. A process redesign proves more disruptive. A regulatory condition changes. The expected benefit becomes less valuable, more expensive, or less attainable.
The project may still be competently managed. It may remain within its approved schedule and budget. Its reporting may be accurate.
Yet the investment premise may be deteriorating.
This is why delivery status and investment validity are different judgments.
Project governance asks whether the work is being delivered responsibly against the approved plan.
Capital governance must also ask whether the current evidence still justifies the next commitment.
That second question should not wait until the project is complete.
From Benefits Realization to Continuing-Investment Validity
Benefits realization is commonly positioned as a post-implementation discipline. The organization delivers the capability and then measures whether the promised outcomes materialize.
That remains important, but it is incomplete.
By the time final benefits can be measured, most of the capital may already have been committed. Contracts may have been extended. Organizational capacity may have been consumed. Legacy systems may have been retired. Operational dependencies may have formed. Decision options may have narrowed.
The more useful governance question is not only whether the original benefits were eventually realized.
It is whether the investment remains supportable while capital is still moving.
I call this Continuing-Investment Validity: the present-tense judgment that the expected outcome, current path, material assumptions, known risks, operating constraints, and remaining commitment still justify continued authorization.
This does not mean reopening the full business case every week. Nor does it imply that every adverse signal should trigger cancellation.
Difficult projects can still create substantial value. Delays may be rational. Additional investment may preserve an important outcome. A pivot may be more responsible than either blind continuation or premature termination.
The purpose is not to automate a verdict.
The purpose is to ensure that continued investment remains connected to current evidence rather than inherited confidence.
Under this model, benefits realization is no longer confined to a retrospective exercise. It becomes part of an active capital-governance discipline.
The organization continually examines whether the conditions required to produce the benefit are strengthening, weakening, changing, or remaining uncertain.
That is a materially different proposition from attempting to calculate every benefit after implementation.
There Must Be a Business Case for Measuring the Business Case
It is easy to assume that more measurement must produce better governance.
That is not necessarily true.
Benefits measurement consumes resources. It may require new data collection, integration across systems, analytical modeling, baseline reconstruction, attribution analysis, operational interviews, management reporting, and professional interpretation.
The more intangible the benefit, the more difficult and expensive the attribution may become.
An organization may be able to determine whether customer satisfaction improved, for example, but still struggle to isolate how much of that improvement resulted from a particular technology investment rather than pricing changes, staffing adjustments, market conditions, process redesign, or unrelated management action.
Likewise, a new platform may contribute to reduced operating cost while also increasing licensing expense, cybersecurity exposure, vendor dependency, training requirements, and support complexity.
A precise answer may be possible.
The cost of obtaining it may not be justified.
Therefore, the relevant question is not:
Can we measure the benefit?
The better question is:
Will obtaining this evidence improve a decision enough to justify the cost of obtaining it?
This introduces an economic test for benefits measurement itself.
The value of measurement can be understood as the expected value of improved decisions, less the full cost of producing, interpreting, governing, and acting on the evidence.
That expected value depends on several conditions.
First, there must be a reasonable probability that the evidence could materially influence a decision. Second, the consequence of making that decision better must be significant enough to matter. Third, the decision must still be actionable. Finally, the cost and delay of obtaining the evidence must remain proportionate to the capital exposure involved.
Spending a modest amount to determine whether another $10 million should be committed may be entirely rational.
Spending hundreds of thousands of dollars to establish, with greater analytical precision, whether a completed and irreversible investment produced $1.7 million or $1.9 million in benefits may not be rational—unless the conclusion will materially affect future investments, contractual recovery, regulatory obligations, litigation, operating strategy, or another consequential decision.
The principle is straightforward:
Measurement should be proportionate to decision consequence.
When no material decision remains, exhaustive retrospective benefits analysis may become little more than expensive historical certainty.
The report may be accurate. It may be professionally produced. It may satisfy curiosity or complete a governance checklist.
It may not create enough value to justify its existence.
When Benefits Measurement Is Worthwhile
Benefits measurement becomes economically useful when it can still change something important.
It may help leadership determine whether to continue or stop spending, scale or constrain a capability, renegotiate a vendor arrangement, correct weak adoption, redesign an operating process, retire an unsuccessful solution, preserve an effective intervention, or improve the assumptions used in future investments.
Measurement may also be necessary where contractual, regulatory, accounting, audit, safety, security, or other professional obligations require evidence regardless of immediate financial return.
Even then, the scope should remain bounded.
The enterprise does not need perfect knowledge about every historical effect. It needs sufficient evidence for the decision, obligation, or learning objective at hand.
This suggests a more disciplined set of questions:
What decision could this measurement change?
How much capital, risk, or operational consequence remains exposed?
How reversible is the decision?
What level of confidence is actually required?
What evidence already exists?
What additional evidence would materially improve judgment?
What would it cost to obtain?
What happens if the enterprise does not obtain it?
These questions convert benefits measurement from a ritual into an investment decision.
They also reveal why traditional benefits-realization programs often fail. The organization attempts to create a comprehensive measurement apparatus without first establishing which decisions the information will support.
Data is collected because the methodology says it should be collected. Reports are produced because governance requires them. Benefit owners are asked to provide updates long after the project has closed.
The machinery continues.
The decision value remains unclear.
AI Changes the Economics of the Problem
The principles behind benefits realization are not new. Treating projects as investments is not new. Comparing actual outcomes with business-case assumptions is not new.
What has changed is the economics of preparing the evidence.
Modern enterprises generate enormous volumes of operational material: financial transactions, tickets, schedules, test results, technical records, customer interactions, risk updates, vendor correspondence, meeting transcripts, decisions, forecasts, and performance measures.
Traditional governance structures cannot continuously reconcile all of this by hand.
Project managers, analysts, finance teams, architects, sponsors, and operational leaders act as human middleware. They retrieve information from different systems, interpret it, resolve terminology, compare versions, reconstruct chronology, and compress the result into executive reporting.
This translation work is necessary, but it introduces delay. It also creates opportunities for context loss, inconsistent interpretation, optimistic compression, and the gradual disappearance of earlier assumptions.
AI can materially reduce that burden.
A properly governed AI environment can help retrieve records, compare versions, trace assumptions, reconstruct decision chronology, identify missing evidence, detect contradictions, and connect operational measures to the propositions in the original business case.
It can ask whether the adoption level assumed in the investment case is appearing in operational data. It can compare forecast cost reductions with actual expenditure. It can identify when a benefit dependency has remained unresolved across multiple steering cycles. It can surface the gradual weakening of vendor language. It can detect when a proof point that once justified confidence has disappeared from later reporting.
This does not require AI to know whether the project should continue.
It requires AI to make the evidence needed for that judgment more visible, current, and traceable.
That distinction matters.
AI does not create the investment-governance principle. It changes the cost, speed, and practical feasibility of exercising it.
The Real Opportunity Is Lower-Cost Decision Intelligence
The strongest argument for AI is not that it enables organizations to measure more things.
That could simply produce cheaper bureaucracy at a larger scale.
The stronger proposition is that AI can reduce the marginal cost of obtaining decision-relevant evidence.
Instead of launching a large retrospective exercise after implementation, the enterprise may be able to maintain selected relationships as the investment proceeds. Evidence already generated through normal operations can be retrieved, compared, and organized around the assumptions that matter.
The business case can remain connected to operating evidence without requiring teams to construct a second administrative system solely for benefits tracking.
This creates a different economic model.
Rather than asking people to measure every promised benefit continuously, AI can help identify the few evidence relationships that may change a consequential decision.
It can surface where costs are rising faster than expected, where adoption is materially below the level required for the benefit, where an operating dependency remains unresolved, where a prior assumption has weakened, or where the expected outcome no longer carries the value originally assigned to it.
Leadership can then determine whether deeper analysis is justified.
In other words, AI can support a staged evidence process.
The first stage is inexpensive signal detection using information the enterprise already possesses.
The second stage is focused examination where the signal, capital exposure, uncertainty, and available decision options justify additional effort.
The third stage is accountable judgment by the people who own the business, professional, and capital consequences.
This is more economically defensible than attempting to maintain exhaustive measurement across every investment.
The objective is not comprehensive benefits accounting.
It is economically proportionate decision intelligence.
What an AI-Enabled Benefits Architecture Could Look Like
An effective architecture would begin by converting the business case from a static narrative into a governed set of material propositions.
Expected benefits would be connected to their assumptions, dependencies, measures, baselines, time horizons, evidence sources, accountable owners, and decision conditions.
The objective would not be to reduce every benefit to a simplistic score. Nor would every proposed benefit require continuous surveillance.
The purpose would be to make the reasoning behind the investment recoverable and to identify which propositions remain consequential to future decisions.
The architecture would then maintain a governed context environment around the initiative. Financial records, operational measures, project evidence, decisions, risks, technical findings, and material communications would remain connected through time.
AI could prepare this material through a controlled process of retrieval, validation, normalization, comparison, and synthesis.
Rather than producing a larger status report or a comprehensive benefits ledger, it would identify the evidence relationships that require accountable attention.
For example:
Which original benefit assumptions remain supported?
Which have weakened or become uncertain?
What evidence is missing?
Which dependencies now threaten the expected return?
Has the cost of achieving the benefit materially changed?
Has the benefit itself become less valuable?
What commitment is the organization about to make next?
Would additional measurement change that decision?
What would the additional measurement cost?
What should leadership examine before capital moves again?
These questions shift governance away from retrospective explanation and toward decision preparedness.
The benefit owner would still matter. Indeed, the role would become more meaningful.
Rather than functioning as the person expected to manually assemble scattered evidence, the benefit owner could focus on interpretation, accountability, corrective action, and the recommendation placed before decision authority.
AI would reduce the administrative burden surrounding accountability without inheriting the accountability itself.
Signal First, Investigation Second
The distinction between a signal and a conclusion becomes essential.
A signal is an observable indication that the official investment narrative may no longer match the evidence relevant to the next decision.
It is not proof. It is not an accusation. It is not a final benefit calculation. It is not an instruction to continue, pivot, or stop.
A signal tells leadership where further attention may be economically justified.
For example, weak adoption data may indicate that the expected benefit is at risk. That signal may justify a limited investigation into training, process fit, user behavior, or operating incentives.
It does not automatically justify an expensive enterprise-wide attribution study.
Similarly, continued spending without corresponding evidence of progress may indicate that the investment thesis deserves examination. That examination should be proportionate to the remaining exposure and the available decision options.
This creates a more disciplined escalation model.
Not every variance deserves investigation.
Not every investigation requires exhaustive measurement.
Not every measurement needs statistical or financial precision.
The depth of analysis should increase only when the expected value of improved judgment justifies the additional burden.
AI can help keep the first stage inexpensive. Human authority determines whether the second stage is warranted.
AI Does Not Arrive with “Benefits Inside” Either
There is an important warning embedded in this opportunity.
Organizations should not repeat the same mistake with AI that they made with previous technology investments.
AI systems do not arrive stamped “benefits inside.”
Purchasing a model, deploying a copilot, building an agent, or creating an enterprise knowledge environment does not automatically produce value.
The benefit depends on where the capability is applied, how work changes, whether decisions improve, whether adoption is sustained, whether risk is controlled, and whether measurable outcomes exceed the cost and complexity introduced.
AI investments must therefore be governed by the same discipline they may help enable.
What belief is being funded?
What operating improvement is expected?
Which assumptions support that expectation?
What evidence would demonstrate progress?
What evidence would indicate that the path is weakening?
What will it cost to obtain that evidence?
Which decisions will the evidence influence?
Who owns interpretation?
Who has authority to continue, constrain, redirect, or stop the investment?
Without those questions, AI becomes another technology category surrounded by ambitious business cases and weak post-approval accountability.
The technology may be new.
The governance failure would be familiar.
AI Can Prepare Judgment. It Cannot Own Judgment.
The most dangerous version of this future would be an automated system declaring that a benefit has or has not been realized and then recommending a capital decision as though the conclusion were objective.
Evidence rarely speaks without context.
Financial results may have multiple causes. Adoption data can be misleading. A delayed benefit may still be attainable. A temporary cost increase may be necessary to create longer-term value. Operational metrics may require professional interpretation.
Legal, accounting, technical, regulatory, workforce, market, and contractual considerations may materially change the meaning of the same evidence.
AI can help prepare the evidence surface.
It cannot inherit the authority of the records it reads. It cannot assume the expertise of every professional domain. It cannot become the accountable executive. It cannot own the consequences of the decision.
The proper relationship is therefore straightforward:
AI can prepare judgment. It cannot own judgment.
Human leaders remain responsible for interpreting uncertainty, considering alternatives, exercising authority, and preserving the rationale behind the decision.
AI makes the work more achievable and potentially more economical.
It does not make accountability optional.
The Dream Must Also Be Economically Rational
The idea that organizations should govern benefits has existed for a long time. The idea that benefit owners should be accountable is also sound.
The reason these ideas so often remain aspirational is not merely weak discipline or poor leadership. The underlying evidence problem has been too fragmented, too manual, and too expensive to manage continuously at enterprise scale.
In many circumstances, organizations may have behaved rationally by not pursuing exhaustive benefits measurement. The cost of connecting every assumption, operational change, financial outcome, and causal relationship may have exceeded the value of the answer.
That limitation should be acknowledged rather than hidden beneath another governance mandate.
AI changes the constraint, but it does not eliminate the economic test.
It can help maintain the relationship among the original business case, changing operational evidence, emerging outcomes, unresolved uncertainty, and the next capital decision at a lower marginal cost.
That does not mean every benefit should now be measured.
It means the enterprise can become more selective, timely, and proportionate about what it measures and why.
The breakthrough is not a better benefits dashboard.
It is not another portfolio score.
It is not an automated verdict.
Nor is it a comprehensive measurement regime imposed on every investment.
It is the ability to maintain a current, traceable relationship between the belief that originally justified an investment and the evidence now available to leadership—at a cost proportionate to the decision being made.
Benefits do not come inside the box.
They must be designed, enabled, evidenced, governed, and ultimately realized through accountable operating change.
But even the evidence has a cost.
AI may finally make benefits governance practical by reducing that cost and focusing attention where better knowledge can still change an important decision.
The measurement must earn its keep.
So must the investment being measured.